Author name: Khalid KHALID

How to Choose Guardians for Your Children in a Will

For parents, making a will is about more than deciding who receives money or property. It can also be an opportunity to set out who you would want to care for your children if you die while they are still under 18.

Choosing a guardian is therefore one of the most important decisions parents can make when preparing a will. The right person will need to be able to provide a safe, stable and supportive home, while also understanding your children's individual needs.

What is a testamentary guardian?

A testamentary guardian is someone appointed by a parent in their will to take responsibility for a child after the parent's death. In England and Wales, testamentary guardianship can give the appointed person parental responsibility where the legal conditions are met. Your will should clearly identify the person you want to act as guardian. It is also sensible to discuss the decision with them before making or updating your will.

What should you consider when choosing a guardian?

There is no single answer that works for every family. You might consider:

Relationship with your children: A close family member or trusted friend may already understand your children's personalities and routines.

Age and health: The guardian should realistically be able to care for your children throughout their childhood.

Location: Consider whether moving your children would mean changing schools, leaving friends or moving away from other family members.

Values and parenting approach: Think about whether the proposed guardian shares important values and would respect the way you want your children raised.

Financial circumstances: Guardians do not necessarily have to use their own money to raise the children. However, the financial arrangements surrounding the children should be considered as part of the wider estate plan.

Can you name more than one guardian?

Parents should take care when deciding whether to appoint one person or more than one person. For example, appointing a couple may seem straightforward, but circumstances can change if their relationship breaks down or one person dies.

It may also be sensible to name replacement guardians in case your first choice cannot or does not wish to act.

What if the other parent survives?

Appointing a guardian in your will does not simply override another person who already has parental responsibility. The legal position depends on who has parental responsibility and the circumstances following the parent's death.

This is one reason why parents with complicated family circumstances should consider taking legal advice when preparing their wills.

Think beyond the appointment

A good estate plan can also consider where money for the children should come from, who should manage that money and when children should receive assets.

Your will can therefore form part of a wider plan designed to protect your children's financial and personal welfare.

Conclusion

Choosing guardians for your children is a decision that deserves careful thought. Consider the person's relationship with your children, their ability to provide long-term care and what would happen if your first choice could not act.

Your will should clearly record your wishes and be reviewed after major changes in your family circumstances. GOV.UK recommends considering who should look after children under 18 when making a will.

How to Choose Guardians for Your Children in a Will Read More »

What Happens to Your Pension When You Die?

Many people assume that a pension automatically forms part of their estate and passes according to their will. That is not necessarily how pension death benefits work.

The treatment of a pension depends on the type of pension, the scheme rules, your age and circumstances at death, and the decisions made by the pension provider or scheme trustees.

Who receives your pension?

For many private pensions, you can nominate someone to receive death benefits. GOV.UK explains that the person who died will usually have nominated a beneficiary with their pension provider. However, the provider may sometimes pay someone else depending on the scheme rules and circumstances.

This means your pension beneficiary nomination should be reviewed alongside your will rather than treated as an afterthought.

Does your pension follow your will?

Not necessarily.

Your will deals with assets that form part of your estate, whereas many pension arrangements operate under their own scheme rules. Consequently, simply naming someone in your will does not necessarily mean that person will receive your pension death benefits.

Keeping beneficiary nominations up to date can therefore be an important part of estate planning.

What about tax?

The tax treatment of inherited pension benefits can depend on several factors.

There is also an important upcoming change.

From 6 April 2027, most unused pension funds and pension death benefits will be brought within the value of a person's estate for Inheritance Tax purposes. Finance Act 2026 has legislated for these changes.There are exceptions. For example, death-in-service benefits payable from registered pension schemes are excluded from these Inheritance Tax changes.

The rules surrounding income tax on inherited pension benefits are separate and can also depend on the circumstances.

Why should you review your pension?

Estate planning is not simply about writing a will.

You should consider:

Your current pension provider

Your nominated beneficiaries

Whether your beneficiaries' circumstances have changed

Your wider estate

Life insurance

Property ownership

Potential Inheritance Tax

The upcoming pension tax changes

Marriage, divorce, separation, the birth of children and the death of a beneficiary can all be reasons to review your arrangements.

What should executors know?

If you die with pension benefits, your personal representatives may need to identify pension arrangements and provide information when dealing with the estate.

From April 2027, personal representatives will have responsibilities relating to reporting and paying Inheritance Tax on pension benefits that fall within the new rules. Conclusion

Your pension can be an important part of your estate planning, but it should not be considered in isolation. Beneficiary nominations, pension scheme rules, income tax and the upcoming Inheritance Tax reforms can all affect what happens after death.

Reviewing your pension arrangements alongside your will can help reduce uncertainty for your family.

What Happens to Your Pension When You Die? Read More »

How Life Insurance Fits Into Your Estate Planning

Life insurance can provide valuable financial protection for your family after your death. However, simply having a policy is not the same as having an effective estate plan.

The way a life insurance policy is owned, who benefits from it and whether it is held in trust can affect how the proceeds are treated.

Why include life insurance in estate planning?

Life insurance can provide money to help dependants deal with financial commitments following a death.

For example, a payout might help with:

Mortgage or housing costs

Household expenses

Children's education

Funeral expenses

Other financial commitments

The policy can therefore form an important part of a family's financial planning.

Does life insurance form part of your estate?

The answer depends on the policy and how it is structured.

HMRC guidance explains that where the deceased is both the life assured and policyholder, the proceeds of the policy can form part of their estate for Inheritance Tax purposes. However, life policies can also be placed in trust. HMRC recognises that life policies held in trust have different considerations and that the trust documents need to be examined to determine the relevant beneficial interests.

What does putting life insurance in trust mean?

A trust is a legal arrangement under which assets are managed by trustees for beneficiaries.

A life insurance policy placed into an appropriate trust may allow the policy proceeds to be dealt with outside the deceased's free estate, depending on the circumstances and trust structure.

However, trusts can have complicated legal and tax consequences. Setting up a trust should therefore not be treated as a simple administrative exercise.

Should your will mention your life insurance?

Your will and life insurance policy should be considered together, but the will does not necessarily control the payment of policy proceeds.

You should check:

Who owns the policy

Who is insured

Who the beneficiaries are

Whether the policy is written in trust

Who the trustees are

Whether circumstances have changed

Review your policy regularly

Estate planning needs to change as life changes.

Marriage, divorce, new children, changes in financial circumstances and changes to your wider estate can all be reasons to review life insurance arrangements.

It is also important to keep policy documents somewhere your family or personal representatives can locate them.

Conclusion

Life insurance can be a useful part of estate planning, particularly where family members depend on your income or where your estate has significant liabilities.

However, ownership, beneficiary arrangements and trusts can affect the tax and legal position. Professional advice can help ensure that the policy works alongside your wider estate plan.

This article provides general information and should not be relied upon as individual legal or tax advice.

How Life Insurance Fits Into Your Estate Planning Read More »

Can You Change the Beneficiaries of Your Will?

Your circumstances can change considerably after you make a will. You may have children, grandchildren, marry, divorce, fall out with someone or simply change your mind about who should inherit.

Fortunately, a will can generally be changed while you have the required capacity and follow the appropriate legal formalities.

Can you simply edit your existing will?

No.

Once a will has been signed and witnessed, you should not simply cross out a beneficiary or write new instructions on the document.

GOV.UK explains that changes to a signed and witnessed will should be made through an official alteration called a codicil, which must be signed and witnessed in the required way.

When should you make a new will?

A codicil can be appropriate for a relatively straightforward change.

However, if you want to make significant changes to several beneficiaries or substantially change your estate plan, making a new will may be more appropriate.

A new will should normally state that previous wills and codicils are revoked.What if you have married or divorced?

Major life changes are an important reason to review your will.

GOV.UK specifically recommends reviewing a will every five years and following significant changes such as marriage, divorce or separation, having a child or the death of an executor.

Marriage can have particularly significant consequences because, in general, marriage cancels an earlier will unless it was made in contemplation of that marriage.

Can someone challenge your decision?

Changing a beneficiary does not automatically make a will invalid.

However, disputes can arise where family members believe a person lacked testamentary capacity, was subjected to undue influence or did not properly understand the document.

This is particularly important where a person makes substantial changes late in life or excludes someone who would otherwise expect to inherit.

What happens after someone dies?

There is also a separate process for changing the distribution of an estate after death.

GOV.UK explains that beneficiaries can sometimes agree to a variation of a deceased person's will, provided the relevant requirements are satisfied. Changes generally need to be completed within two years of death for certain tax purposes. This is different from changing your own will while you are alive.

Conclusion

If you want to change beneficiaries in your will, do not simply amend the original document by hand.

Depending on the extent of the change, you may need a properly executed codicil or a completely new will. Reviewing your will regularly can help ensure that it continues to reflect your wishes.

Can You Change the Beneficiaries of Your Will? Read More »

What Does an Executor Actually Have to Do Before Distributing an Estate?

Being named as an executor in a will does not simply mean handing money and property to beneficiaries.

An executor has an important legal role in administering the deceased person's estate. There can be several steps to complete before assets can safely be distributed.

Find the will

The first step is usually to locate the deceased's original will and confirm who has been appointed as executor.

GOV.UK states that an executor named in a will can apply for probate and that the original will is normally required for the application.

Identify the estate's assets and debts

The executor needs to establish what the deceased owned and what they owed.

This may include:

Bank accounts

Investments

Property

Vehicles

Personal possessions

Pensions and death benefits

Life insurance

Loans

Credit cards

Mortgages

Household bills

Tax liabilities

The estate may be more complicated than it initially appears.

Establish whether probate is required

Probate gives the personal representative the legal authority to deal with the deceased's property, money and possessions in appropriate cases. The executor may need to apply for a Grant of Probate before organisations will release certain assets.

Deal with Inheritance Tax

Before applying for probate, the estate generally needs to be valued for Inheritance Tax purposes.

GOV.UK explains that some estates require full details to be reported to HMRC using form IHT400, while others may qualify as excepted estates. Where Inheritance Tax is due, payment arrangements may need to be addressed before probate is granted.

Pay debts and expenses

An executor should not normally distribute the estate simply because beneficiaries are waiting for their inheritance.

Outstanding liabilities need to be identified and dealt with. Funeral expenses, debts, taxes and administration costs can all affect what is ultimately available to beneficiaries.

Distribute the estate

Once the estate has been properly administered, the executor can distribute assets according to the will.

The executor should keep appropriate records showing what assets were collected, what liabilities were paid and what beneficiaries received.

What if there is a dispute?

If there is a dispute about the will, debts, beneficiaries or the administration of the estate, distribution may need to be delayed until the issue is resolved.

An executor should not ignore a potential claim simply because the will appears straightforward.

Conclusion

An executor's job involves much more than obtaining probate and handing out inheritance.

They may need to identify assets, value the estate, deal with tax, settle debts, obtain probate, keep records and distribute the remaining estate correctly.

What Does an Executor Actually Have to Do Before Distributing an Estate? Read More »

What Happens to Jointly Owned Property When One Owner Dies?

Property ownership can become particularly important when someone dies.

A common misconception is that a person's share of jointly owned property will always pass according to their will. That depends on how the property is owned.

In England and Wales, property can generally be held as joint tenants or tenants in common.

What happens if you are joint tenants?

When property is owned as joint tenants, the owners have equal rights to the whole property.

GOV.UK explains that when one joint tenant dies, the property automatically passes to the surviving owner or owners. A joint tenant therefore cannot normally use their will to leave their interest in the property to someone else.This is known as the right of survivorship.

What happens if you are tenants in common?

Tenants in common own separate shares in the property.

Those shares can potentially pass under the owner's will rather than automatically passing to the surviving owner.

For example, two people might own a property as tenants in common in equal shares. If one dies, their share may pass to the beneficiary named in their will, subject to the terms of the will and the wider legal circumstances.

Why does the distinction matter?

The difference can have major consequences for estate planning.

A person might believe they are leaving their home to their children through their will, only to discover that the property is jointly owned in a way that causes the surviving owner to receive it automatically.

This is why property ownership should be reviewed alongside a will.

Can ownership be changed?

In some circumstances, joint owners may be able to change how they hold a property.

However, changing the ownership structure can have legal, financial and tax consequences.

It is therefore important to understand the existing title and beneficial ownership before making changes.

What happens during probate?

The treatment of jointly owned property can affect the estate's value and the assets that personal representatives need to administer.

If the property passes automatically to a surviving joint owner, it may not form part of the estate in the same way as an asset that passes under the will. However, property ownership can have wider Inheritance Tax implications, so the overall circumstances need to be considered.

Conclusion

If you own property jointly, do not assume that your will alone determines what happens to your share when you die.

Understanding whether you are joint tenants or tenants in common is an important part of estate planning.

GOV.UK recommends seeking legal advice where property ownership arrangements are complicated.

What Happens to Jointly Owned Property When One Owner Dies? Read More »

Can You Make a Will for Someone Else? Understanding Testamentary Capacity

Making a will is a personal legal act. A family member cannot simply write or sign a will on behalf of another person because they believe it reflects what that person would have wanted.

The person's capacity to make a will is therefore extremely important.

What is testamentary capacity?

Testamentary capacity refers to the mental ability required to make a valid will.

HMRC guidance referring to the established legal test states that the person making the will must understand that the document will operate after their death, understand the broad effect of what they are doing, have an understanding of the property being disposed of and understand the people who may have claims on their estate.

Does an illness automatically mean someone lacks capacity?

No.

A diagnosis or physical illness does not automatically mean that a person lacks testamentary capacity.

The important question is whether the person has the necessary understanding at the relevant time.

GOV.UK also explains that someone who has lost mental capacity to manage their finances may still have the ability to make a will.

What if someone cannot make a will themselves?

If a person cannot make or change a will themselves, an application can be made to the Court of Protection for a statutory will.

The Court of Protection can authorise a will or changes to an existing will where the person is unable to make the decision themselves.

The application process can involve evidence about the person's circumstances, their existing will, their assets and the proposed arrangements.

Why can capacity become a legal issue?

Capacity disputes can arise after someone's death.

For example, family members might question a will where:

It was made shortly before death

The person was seriously unwell

The will made significant changes

A beneficiary became substantially better off

Someone else was heavily involved in preparing the document

These circumstances do not automatically make a will invalid, but they may require careful examination.

What can help reduce future disputes?

Where there may be concerns about capacity, proper will preparation and evidence can be particularly important.

A professional will-making process can help establish what the person understood and whether the instructions genuinely came from them.

Conclusion

You cannot simply make a normal will for another adult because they are elderly, ill or unable to manage their affairs.

If someone lacks the capacity to make a will, the appropriate route may involve the Court of Protection and a statutory will.

Can You Make a Will for Someone Else? Understanding Testamentary Capacity Read More »

How to Prepare for a Probate Solicitor: Documents and Information You May Need

Dealing with probate after someone dies can feel overwhelming, particularly when family members are also dealing with grief.

One way to make the process more efficient is to gather as much relevant information as possible before meeting a probate solicitor.

The exact documents required will depend on the estate, but certain information is commonly important.

The original will

If the deceased left a will, the original document is particularly important.

GOV.UK states that an executor applying for probate normally needs to provide the original will and that the Probate Registry keeps it as a public record after the grant is issued. You should also provide any codicils or other relevant documents.

Death certificate

A death certificate will normally be needed as part of dealing with the deceased's affairs.

If the death occurred outside England and Wales, or an interim certificate has been issued by a coroner, specific requirements may apply to the probate application.

Bank and savings information

Try to collect details of:

Current accounts

Savings accounts

ISAs

Investment accounts

Premium bonds

Other financial assets

Statements can help establish balances and transactions around the date of death.

Property information

For property, gather documents showing:

The address

Ownership details

Mortgage information

Property valuation

Any rental arrangements

Relevant insurance

Where a property is jointly owned, it is particularly important to establish whether it was held as joint tenants or tenants in common.

Pension and life insurance information

Locate pension statements and beneficiary nomination information.

Also provide details of life insurance policies, including whether a policy is held in trust.

This is increasingly important because most unused pension funds and pension death benefits are due to come within the Inheritance Tax regime from 6 April 2027.

Debts and liabilities

A probate solicitor will also need information about liabilities.

This can include:

Mortgages

Credit cards

Personal loans

Utility bills

Tax liabilities

Care costs

Other outstanding debts

Gifts made before death

Information about significant gifts made during the deceased's lifetime can also be relevant when calculating the estate for Inheritance Tax purposes.

GOV.UK explains that certain estates may require details of gifts and other information to be reported to HMRC.

Make a simple estate checklist

Before your first meeting, creating a simple list of assets, debts, policies and documents can save considerable time.

Do not worry if you cannot find everything. Tell the solicitor what you know and identify anything that is missing.

Conclusion

Preparing for a probate solicitor does not mean you need to have every aspect of the estate worked out before the first appointment.

The most useful starting point is to gather the original will, death certificate, property information, bank and investment details, pension and insurance documents, debts and information about significant gifts.

The more complete the information, the easier it can be to identify what needs to be dealt with during the administration of the estate.

How to Prepare for a Probate Solicitor: Documents and Information You May Need Read More »

Making a Will During Illness or Hospitalisation

Serious illness can cause people to think about matters they may previously have postponed, including what should happen to their property, savings and possessions after death.

For some people, that conversation begins while they are receiving treatment in hospital.

This can create an understandable sense of urgency. A patient may realise that they have never made a will, that an existing will no longer reflects their circumstances, or that important changes are needed following marriage, separation, changes within the family or changes to their assets.

Being ill or admitted to hospital does not automatically prevent somebody from making or changing a will.

However, additional care may be required.

A valid will must satisfy legal requirements, and questions surrounding mental capacity, undue influence, voluntariness and proper witnessing can become particularly important when a person is seriously unwell.

Where time is limited, obtaining legal advice promptly can help ensure that the person’s wishes are properly understood and that the will is prepared and executed correctly.

This article explains some of the important considerations when making a will during illness or hospitalisation in England and Wales.

Can You Make a Will While in Hospital?

Yes.

There is no general rule preventing somebody from making a will simply because they are in hospital.

A person may be receiving treatment, recovering from an operation or living with a serious illness and still be capable of making a valid will.

The important questions concern whether the legal requirements for a valid will are satisfied.

Generally, the person must:

  • Be aged 18 or over;
  • Make the will voluntarily;
  • Have the necessary mental capacity;
  • Put the will in writing;
  • Sign it using the legally required procedure; and
  • Have the signature properly witnessed by two adults.

Hospitalisation itself does not remove a person’s ability to satisfy these requirements.

Why Might Someone Need a Will Urgently?

There are many reasons somebody may decide to make or update a will during illness.

They may never previously have made one.

Alternatively, an existing will may have been prepared many years earlier and no longer reflect their current circumstances.

For example, there may have been changes involving:

  • Marriage or civil partnership;
  • Separation or divorce;
  • Children or grandchildren;
  • Property ownership;
  • Business interests;
  • Financial circumstances;
  • Intended beneficiaries;
  • Executors; or
  • Particular gifts.

A serious diagnosis can also prompt somebody to review arrangements that they had always intended to address “later”.

Where the person’s health is deteriorating, time can become important.

However, urgency should not mean that the legal safeguards surrounding wills are ignored.

What Happens If Someone Dies Without a Will?

A person who dies without leaving a valid will dies intestate.

Their estate is then distributed according to the intestacy rules.

Those rules determine which relatives are entitled to inherit and in what circumstances.

This may not produce the result the deceased person would have chosen.

For example, unmarried partners do not automatically have the same inheritance rights under intestacy as spouses or civil partners.

Making a will allows somebody to record their own wishes rather than relying on the statutory rules.

For somebody facing serious illness, that can provide important clarity for their family.

Does Serious Illness Mean Someone Lacks Mental Capacity?

No.

Physical illness and mental capacity are not the same thing.

A person can be seriously physically unwell while remaining entirely capable of understanding and making decisions.

Similarly, being elderly does not automatically mean that somebody lacks capacity.

The relevant issue is the person’s ability to make the particular decision at the relevant time.

Government guidance concerning mental capacity emphasises that capacity should not simply be assumed to be absent because somebody has an illness or disability.

A person should generally be presumed capable of making their own decisions unless the contrary is established.

What Is Mental Capacity?

Broadly, mental capacity concerns a person’s ability to make a particular decision.

Under the Mental Capacity Act framework, relevant considerations include whether somebody can understand information needed for a decision, retain it sufficiently to make that decision, weigh the relevant information and communicate their decision.

Capacity is also decision-specific and time-specific.

Someone might be able to make one decision but not another.

Likewise, a person’s capacity may fluctuate.

Illness, medication, pain, fatigue or confusion may potentially affect somebody differently at different times.

This can become particularly relevant in a hospital environment.

Is Capacity to Make a Will Different?

The capacity required to make a will is often referred to as testamentary capacity.

Will-making has its own established legal principles, and professional assessment may require careful consideration of whether the person understands the nature and effect of making a will, the broad extent of their estate and the people whose potential claims they ought to consider.

The fact that somebody needs assistance with other decisions does not necessarily mean they cannot make a will.

Indeed, government guidance concerning statutory wills expressly recognises that somebody who has lost capacity to manage their finances may still retain the ability to make their own will.

Capacity therefore needs to be considered specifically in relation to the will being made.

Why Can Capacity Become an Issue in Hospital?

Hospital patients may be experiencing circumstances that can affect decision-making temporarily or permanently.

For example, a person may be affected by:

  • Serious illness;
  • Cognitive impairment;
  • Confusion;
  • A brain injury;
  • Effects of medical treatment;
  • Fatigue; or
  • Other factors affecting their ability to understand or communicate.

This does not mean that every hospital patient has questionable capacity.

It means that where there is a genuine concern, appropriate steps may need to be taken to assess and document the position.

In some circumstances, medical input may be appropriate.

Can a Solicitor Visit Someone in Hospital?

Depending on the firm and circumstances, solicitors may be able to arrange appointments away from their office, including hospital visits.

This can be particularly useful where somebody cannot travel because of their health.

Where the matter is urgent, the solicitor will normally need sufficient information to understand the person’s circumstances and wishes before the will can be prepared.

Practical arrangements may also need to be coordinated with the hospital, particularly where the patient is undergoing treatment or there are restrictions on visitors.

Contacting a solicitor as early as possible is therefore preferable to waiting until the situation becomes critical.

Why Might the Solicitor Want to Speak to the Patient Alone?

Family members often help an ill relative contact a solicitor.

There is nothing unusual about that.

However, the solicitor may need to speak privately with the person making the will.

This can be important for several reasons.

The solicitor needs to establish the client’s own instructions.

They may also need to consider whether the client understands what they are doing and whether their decisions are being made voluntarily.

If another person remains in the room answering questions or directing the conversation, it may become harder to establish that the will genuinely represents the client’s independent wishes.

A private conversation can therefore be an important safeguard.

What Is Undue Influence?

A will must reflect the testator’s own intentions.

Concerns can arise where another person pressures or coerces somebody into making a will or changing its contents.

This can become especially sensitive where a person is seriously ill or dependent on relatives or carers.

A family member may genuinely believe they are helping while inadvertently dominating discussions.

More serious cases may involve allegations that somebody deliberately pressured a vulnerable person for financial benefit.

A solicitor preparing a will should therefore obtain instructions from the client and be alert to circumstances that raise concerns about voluntariness or influence.

Can a Family Member Tell the Solicitor What the Will Should Say?

Family members can provide useful practical information, particularly where the client has mobility or communication difficulties.

But the will must ultimately reflect the wishes of the person making it.

A relative cannot simply instruct a solicitor to prepare somebody else’s will according to the relative’s preferences.

Where the client has capacity, the instructions must come from the client.

If the person no longer has the capacity required to make a will, a different legal process may need to be considered.

What If the Person Cannot Physically Sign?

Physical difficulty signing does not necessarily make it impossible to execute a will.

Current GOV.UK guidance confirms that someone can sign on the will-maker’s behalf where the will-maker is unable to sign personally, provided the required conditions are followed.

However, this is an area where professional assistance can be particularly valuable.

The execution must still comply with the legal formalities, and it should be clear that the signature is being made on the person’s behalf and at their direction.

Where health is poor, careful documentation can help reduce uncertainty later.

How Many Witnesses Are Required?

For an ordinary will in England and Wales, two adult witnesses are required.

The will-maker signs in the presence of both witnesses.

The witnesses then sign in the will-maker’s presence.

The required procedure must be followed correctly.

This can require some practical planning in a hospital, where access to the patient may be limited.

Suitable independent witnesses therefore need to be identified before execution.

Who Should Witness a Will?

Choosing witnesses carefully is important.

A beneficiary under the will should generally not act as a witness.

Nor should the spouse or civil partner of somebody receiving a gift under the will.

GOV.UK guidance warns that a person cannot leave their witnesses, or the witnesses’ married partners, anything under the will.

Using appropriate independent witnesses can help avoid problems.

In a hospital setting, the solicitor can advise on suitable arrangements rather than assuming that whoever happens to be present should witness the document.

Can Hospital Staff Witness a Will?

Whether an individual member of hospital staff can appropriately act as a witness will depend on the circumstances and relevant hospital policies.

There may be practical or professional restrictions.

It is therefore unwise to assume that doctors or nurses will automatically be available or willing to witness a will.

Where possible, witnessing arrangements should be discussed in advance.

A solicitor arranging an urgent hospital will can help identify what is required and coordinate an appropriate execution process.

What If the Patient Is Too Tired?

Capacity and ability to give instructions may vary during serious illness.

A person may be alert in the morning but exhausted after treatment.

Medication or medical procedures may also affect how well somebody can concentrate.

Where possible, a meeting should take place when the client is best able to engage with the process.

Government mental-capacity guidance recognises the importance of timing and circumstances when supporting people to make decisions.

A solicitor may therefore consider whether another time would allow the client to understand and communicate more effectively, provided the matter can safely wait.

What If Capacity Fluctuates?

Some medical conditions can cause capacity to fluctuate.

A person may be confused at one point but much clearer later.

The relevant question is whether they have the required capacity when the decision is being made.

This can make timing particularly important.

Where the circumstances allow, it may be appropriate to arrange discussions for a period when the person is more alert.

Where there is uncertainty, medical evidence may also be considered.

Can a Doctor Assess Capacity?

Medical professionals can provide valuable evidence where capacity is genuinely in question.

Government guidance recognises that doctors and other medical professionals may assist with capacity assessments.

For legal decisions such as making a will, the solicitor will need to be satisfied about the client’s ability to give valid instructions and make the will.

Where illness or cognitive difficulties create uncertainty, the solicitor may consider medical input appropriate.

The precise approach will depend on the circumstances.

Why Is Record-Keeping Important?

A will may not be examined closely until after the person who made it has died.

If somebody later challenges the will, questions might be raised about:

  • The person’s capacity;
  • Whether they understood the document;
  • Whether they were pressured;
  • Whether the will accurately recorded their instructions; or
  • Whether it was executed correctly.

Where a will is prepared during serious illness, careful professional records can therefore be particularly important.

The solicitor may record the circumstances surrounding the instructions and execution and any steps taken to address capacity or undue-influence concerns.

What Information Does a Solicitor Need?

Even when a will is urgent, the solicitor needs enough information to understand what the client wants.

This may include details of:

  • Family members;
  • Intended beneficiaries;
  • Property;
  • Savings and investments;
  • Business interests;
  • Overseas assets;
  • Existing wills;
  • Executors;
  • Specific gifts; and
  • Any people the client wishes to provide for or intentionally exclude.

Complicated circumstances may require additional discussion.

Providing accurate information as early as possible can help when time is limited.

What If There Is Already a Will?

The solicitor should normally be told about any existing will.

The client may simply need to review whether it still reflects their wishes.

If substantial changes are required, making a new will may be appropriate.

Smaller changes can sometimes be made using a codicil, although the correct approach depends on the circumstances.

A new will can revoke an earlier one if properly drafted to do so.

Professional advice can help avoid creating conflicting documents or uncertainty about which version should apply.

Can a Will Be Changed at the Last Minute?

Potentially, yes, provided the person still has the required capacity and the legal formalities can be completed.

But last-minute changes can create additional risks.

There may be less time to obtain instructions, review complicated assets, consider tax consequences or investigate concerns about capacity.

Sudden substantial changes benefiting one family member while excluding others can also potentially lead to questions after death.

None of this means that a late will is automatically invalid.

It simply means that careful professional preparation can become particularly valuable.

What If the Person Is Very Close to Death?

Where somebody may have only a short time to live, the situation can become extremely urgent.

A solicitor should be contacted immediately.

The priority is to determine whether the person can still give valid instructions and whether there is enough time to prepare and properly execute the will.

Family members should avoid trying to answer questions on the person’s behalf where the individual can communicate their own wishes.

The fact that death is expected soon does not remove the requirements relating to capacity, voluntariness or execution.

What Happens If the Person No Longer Has Capacity?

If somebody no longer has the testamentary capacity required to make or change their own will, relatives cannot simply make one for them.

Instead, it may be possible to apply to the Court of Protection for a statutory will.

A statutory will is a will authorised by the Court of Protection on behalf of somebody who lacks the capacity to make one themselves.

The process requires evidence and court approval.

It is fundamentally different from an ordinary will made personally by someone with testamentary capacity.

What Is a Statutory Will?

A statutory will can be considered where a person cannot make or change a will themselves because they lack the necessary capacity.

The Court of Protection considers the application.

Government guidance indicates that the applicant must provide supporting information, including evidence concerning the person’s lack of capacity and details of the proposed will.

The Court determines whether the proposed arrangements should be authorised.

This is not simply a way for relatives to choose how another person’s estate should be distributed.

The court process exists to protect the interests of the person who lacks capacity.

Are Emergency Statutory Will Applications Possible?

Yes.

GOV.UK guidance specifically recognises that an emergency application can be made to the Court of Protection where the person concerned has only a short time to live.

However, court involvement is inevitably different from being able to make a personal will while capacity remains.

This is another reason early estate planning is preferable wherever possible.

Leaving matters until somebody is critically ill can significantly reduce the available options.

Should You Wait Until You Are Ill to Make a Will?

Ideally, no.

A hospital will can be valid and sometimes urgent circumstances cannot be avoided.

But making a will while healthy usually provides more time to think carefully about decisions, gather information and obtain advice.

There is also less risk that questions will arise about the effects of illness, medication, fatigue or cognitive impairment.

A will can be reviewed later if circumstances change.

Making one earlier therefore does not prevent future changes.

Will an Urgent Will Automatically Be Challenged?

No.

A will is not automatically invalid or suspicious merely because it was made shortly before death.

People are entitled to make or change wills while they have the necessary capacity and satisfy the legal requirements.

However, circumstances surrounding a late will can sometimes receive closer scrutiny, particularly if substantial changes were made or family members disagree about the person’s capacity or independence.

Following proper procedures and obtaining professional advice can help provide clearer evidence about how and why the will was made.

What Can Families Do to Help?

If a relative in hospital says they want to make a will, family members can help with practical arrangements without taking over the decision-making process.

They might:

  • Help locate an existing will;
  • Find contact details for a solicitor;
  • Gather basic information about assets where requested;
  • Help arrange an appointment;
  • Inform hospital staff that a professional visitor may attend; and
  • Give the client privacy to speak with the solicitor.

The goal should be to help the person express their own wishes.

Conclusion

Being seriously ill or admitted to hospital does not automatically prevent somebody from making a will.

What matters is whether the person has the required testamentary capacity, is acting voluntarily, can communicate their wishes and can complete the will using the legally required signing and witnessing procedure.

However, illness can make the process more complicated.

Capacity may fluctuate. Medication, treatment or fatigue may affect the person’s ability to engage at particular times. Family members may be heavily involved in their care, creating a need to ensure that instructions genuinely reflect the client’s own wishes. Practical arrangements must also be made for appropriate witnesses.

Where there is genuine doubt about capacity, medical input may be appropriate.

If the person cannot physically sign, alternative arrangements may still be possible provided the legal requirements are carefully followed.

Where somebody has already lost the capacity required to make their own will, relatives cannot simply create one for them. An application to the Court of Protection for a statutory will may instead need to be considered.

The most important practical lesson is not to delay.

Making or reviewing a will while healthy generally provides more time and fewer complications. But where illness has already occurred, obtaining specialist legal advice promptly can help establish what options remain available and ensure that the person’s wishes are handled with appropriate care.

Making a Will During Illness or Hospitalisation Read More »

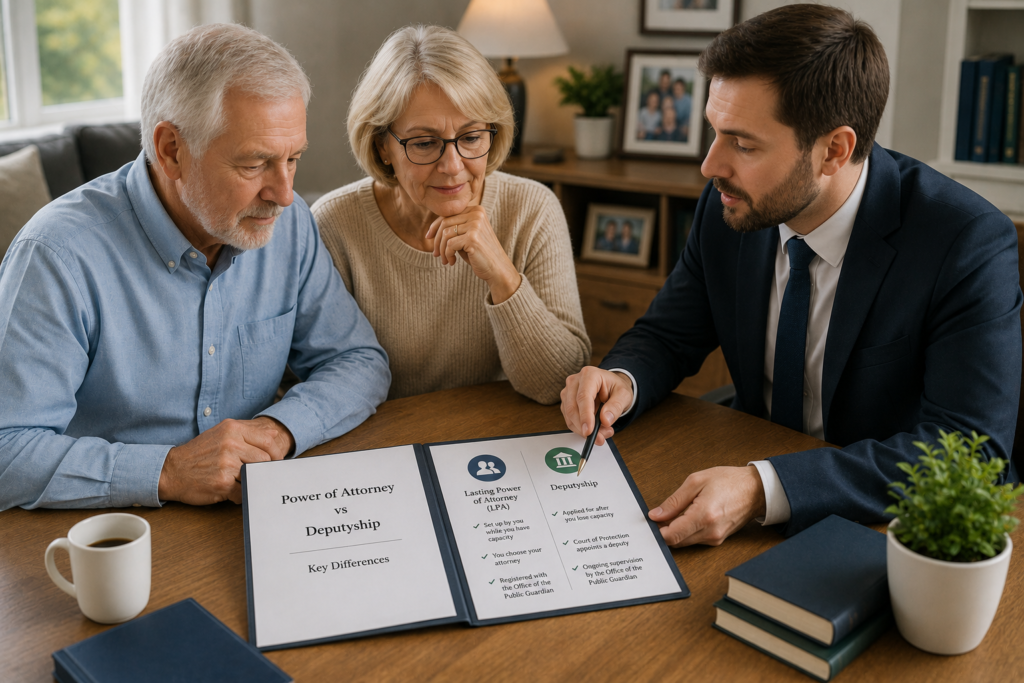
Power of Attorney vs Deputyship: Key Differences

Planning for a time when you might be unable to make certain decisions for yourself can feel uncomfortable, but putting appropriate arrangements in place can make an enormous practical difference for you and your family.

Two terms frequently encountered in this area are Lasting Power of Attorney (LPA) and deputyship.

Both can involve another person making decisions for somebody else, but they are not interchangeable.

A Lasting Power of Attorney is generally created in advance by somebody who has the mental capacity to decide who they want to appoint as their attorney.

Deputyship usually becomes relevant after a person has already lost the mental capacity to make particular decisions and there is no appropriate power of attorney covering what needs to be done. An application is then made to the Court of Protection, which decides whether a deputy should be appointed and what authority that deputy should have.

Understanding the difference can help families appreciate why planning ahead may be valuable and what options may remain available if capacity has already been lost.

This article explains the key differences between Lasting Powers of Attorney and deputyship in England and Wales.

What Is a Lasting Power of Attorney?

A Lasting Power of Attorney is a legal document that allows an individual to appoint one or more trusted people to make certain decisions on their behalf.

The person creating the LPA is called the donor.

The people appointed are called attorneys.

An LPA is made while the donor has the mental capacity required to create it.

This allows the donor to decide personally who should act for them and to make choices about how that authority should operate.

The LPA must be registered with the Office of the Public Guardian before it can be used.

What Are the Two Types of LPA?

There are two types of Lasting Power of Attorney in England and Wales:

  • Property and financial affairs LPA
  • Health and welfare LPA

A person can choose to make either one or both.

They cover different types of decisions.

What Does a Property and Financial Affairs LPA Cover?

A property and financial affairs LPA can give attorneys authority concerning the donor’s money and property.

Depending on the terms of the LPA, this may include matters such as:

  • Managing bank or building society accounts;
  • Paying bills;
  • Collecting pensions or benefits;
  • Managing investments;
  • Dealing with property; and
  • Handling other financial affairs.

Once registered, a property and financial affairs LPA can potentially be used while the donor still has capacity if the donor gives permission.

This can make it useful not only following loss of capacity but also where somebody remains mentally capable but needs practical assistance.

What Does a Health and Welfare LPA Cover?

A health and welfare LPA concerns decisions relating to personal welfare.

Depending on the authority given, this can include decisions about:

  • Daily routine;
  • Medical care;
  • Where the donor should live; and
  • Certain care arrangements.

A health and welfare LPA can only be used when the donor lacks capacity to make the particular decision themselves.

The donor can also decide whether their attorneys should have authority to make decisions concerning life-sustaining treatment.

This is an important choice that should be considered carefully when preparing the LPA.

What Is a Deputy?

A deputy is somebody appointed by the Court of Protection to make certain decisions for a person who lacks the mental capacity to make those decisions themselves.

The person who lacks capacity is often referred to as P in Court of Protection proceedings.

Deputyship may become necessary where important decisions need to be made but no suitable LPA or other authority is already in place.

Unlike an attorney, a deputy is not appointed personally by the individual through an LPA.

The Court decides whether the appointment should be made and what powers the deputy should have.

What Types of Deputyship Are There?

Deputyship can broadly concern:

  • Property and financial affairs; or
  • Personal welfare.

Property and financial affairs deputyships are more commonly encountered.

The Court of Protection is generally more cautious about appointing personal welfare deputies.

Rather than granting broad ongoing authority over welfare matters, the Court may in some situations prefer to make a decision concerning a specific issue.

Whether deputyship is appropriate depends on the person’s circumstances and the decisions that need to be made.

The Biggest Difference: When Are They Created?

Timing is one of the most important distinctions.

An LPA is created before the donor loses the mental capacity required to make it.

Deputyship generally becomes relevant after capacity has already been lost in relation to the decisions that need to be made.

This distinction can determine which option is available.

If somebody still has the required capacity, they may be able to choose their attorneys and create an LPA.

If they no longer have that capacity, relatives cannot simply create an LPA on their behalf.

A Court of Protection application may instead need to be considered.

Who Chooses the Decision-Maker?

With an LPA, the donor chooses.

They can decide who they trust to act as their attorney.

This might be:

  • A spouse or civil partner;
  • An adult child;
  • Another relative;
  • A trusted friend; or
  • An appropriate professional.

Eligibility requirements apply, and financial attorneys must not be subject to certain bankruptcy or debt restrictions.

The important point is that the donor makes the choice while they have capacity.

With deputyship, the proposed deputy can apply, but the Court of Protection decides whether that person should be appointed.

Why Does Choosing Your Own Attorney Matter?

Allowing someone else to make important decisions about your finances, property, care or welfare involves considerable trust.

Different people may have very different ideas about who they would want to perform that role.

Someone might trust one child with financial matters but prefer another person to be involved in welfare decisions.

Another individual may prefer a professional to deal with complicated finances.

Creating LPAs gives the donor an opportunity to make those choices personally.

If no LPA exists and capacity is later lost, the individual may no longer be able to determine who should receive legal authority.

Can Family Members Automatically Take Over?

No.

This is a common misunderstanding.

Being somebody’s spouse, civil partner, parent or adult child does not automatically provide unrestricted legal authority to manage all of their affairs if they lose capacity.

For example, organisations dealing with a person’s individual financial accounts may require appropriate legal authority before allowing another person to manage them.

Families can therefore discover during a crisis that their relationship to the person does not, by itself, provide the authority they expected.

An LPA or Court of Protection order can provide a formal legal framework.

What If Someone Has Already Lost Capacity?

If a person no longer has the capacity required to make an LPA, it is generally too late for them to create one.

The family should then consider what legal authority is actually needed.

In some cases, an application to the Court of Protection for deputyship may be appropriate.

The Court will consider the application and evidence concerning the person’s capacity and circumstances.

The fact that somebody is a close relative does not guarantee that they will automatically be appointed.

The Court’s focus is on protecting the person who lacks capacity.

How Is Mental Capacity Assessed?

Mental capacity is decision-specific.

A person should be assumed to have capacity unless it is established that they lack it.

A person is not to be treated as unable to make a decision merely because they make a decision others consider unwise.

Before concluding that someone cannot make a decision, appropriate steps should also be taken to help them make it.

Broadly, the Mental Capacity Act considers whether a person can understand the relevant information, retain it sufficiently, use or weigh it as part of the decision-making process and communicate their decision.

Capacity can also fluctuate.

This means the assessment needs to focus on the particular decision and the relevant time.

Does a Diagnosis Automatically Mean Someone Lacks Capacity?

No.

A medical diagnosis does not automatically determine capacity for every decision.

Someone living with dementia, for example, may retain capacity to make some decisions.

Similarly, a person with a brain injury or other condition may have different levels of capacity depending on the nature and complexity of the decision.

The law focuses on the person’s ability to make the specific decision rather than simply applying a label based on diagnosis.

This distinction can be crucial when considering whether an LPA can still be made.

Who Can Be an Attorney?

An attorney must meet applicable eligibility requirements.

For an LPA, attorneys must generally be aged 18 or over.

Different considerations can apply depending on the type of LPA.

For a property and financial affairs LPA, restrictions can apply where a proposed attorney is bankrupt or subject to certain debt-relief arrangements.

The donor should also consider practical suitability.

Being legally eligible does not necessarily mean somebody is the right choice.

The attorney should be trustworthy, capable of handling the responsibility and willing to act.

Who Can Be a Deputy?

A deputy must generally be aged 18 or over.

Deputies are often family members or friends, although professionals can also be appointed in appropriate circumstances.

For property and financial affairs appointments, the Court may consider whether the proposed deputy has the skills and reliability needed to manage the person’s finances.

The Court can refuse to appoint a proposed deputy if it considers that appointment inappropriate.

Again, deputyship is a court appointment rather than an automatic entitlement arising from family relationship.

How Are Attorneys Supervised?

Attorneys have legal responsibilities and must follow the Mental Capacity Act 2005 and the Code of Practice.

They must act in accordance with the authority given by the LPA.

Where the donor lacks capacity to make a particular decision, attorneys must act in the donor’s best interests.

The Office of the Public Guardian can investigate concerns about the actions of an attorney.

Serious concerns may ultimately be referred to the Court of Protection.

An LPA therefore gives authority, but that authority is accompanied by duties and safeguards.

How Are Deputies Supervised?

Deputies are subject to supervision by the Office of the Public Guardian.

The level of supervision can depend on the circumstances.

Deputies may need to provide reports explaining decisions they have made and how they have managed the person’s affairs.

Property and financial affairs deputies may also be required to arrange a security bond.

The bond is designed to provide financial protection if the deputy mismanages the person’s finances in a way that causes loss.

These ongoing requirements are one of the practical differences between deputyship and an LPA.

Does a Deputy Have Unlimited Authority?

No.

A deputy can only act within the authority granted by the Court of Protection.

The deputyship order sets out what the deputy is permitted to do.

If a decision falls outside those powers, a further application to the Court may be required.

Deputies must also comply with the Mental Capacity Act and act in the person’s best interests.

Appointment as deputy therefore does not provide unrestricted control over another person’s life or property.

Does an Attorney Have Unlimited Authority?

No.

An attorney’s powers are determined by the type and terms of the LPA and the law.

The donor may also include certain instructions or preferences.

Attorneys must comply with their legal duties and cannot simply treat the donor’s assets as their own.

Restrictions also exist around particular transactions, including certain gifts.

Professional advice may be necessary where an attorney is uncertain whether a proposed action falls within their authority.

How Long Does an LPA Take?

An LPA cannot be used until it has been registered with the Office of the Public Guardian.

Registration therefore needs to be factored into planning.

It is usually preferable to create and register an LPA before it is urgently needed rather than waiting until a crisis develops.

If capacity is lost before an LPA has been made, the family cannot solve the problem simply by preparing one retrospectively.

That is when the more formal Court of Protection process may become necessary.

How Long Does Deputyship Take?

Deputyship requires a Court of Protection application.

The process involves forms, evidence and a judicial decision.

The time required can depend on the circumstances and whether the application is disputed or complicated.

Because the family may need authority urgently, discovering that deputyship is required can create practical difficulties.

In genuinely urgent situations, other Court of Protection procedures may potentially be available, but specialist advice should be obtained.

Advance planning through an LPA can avoid the need for a standard deputyship application in many circumstances.

Which Is More Expensive?

The cost structures are different.

Making an LPA involves registration fees payable to the Office of the Public Guardian, subject to any applicable fee reductions or exemptions, together with professional fees if a solicitor is instructed.

Deputyship involves a court application and may involve:

  • Court fees;
  • Assessment fees;
  • Annual supervision fees;
  • Security bond costs for financial deputies; and
  • Legal or professional fees where applicable.

Costs vary according to the circumstances.

The key distinction is that deputyship is an ongoing court-supervised arrangement, whereas an LPA is created by the donor in advance and registered with the Office of the Public Guardian.

Can You Have More Than One Attorney?

Yes.

A donor can appoint more than one attorney.

They can specify how multiple attorneys should make decisions.

They may be appointed:

  • Jointly, requiring them to make specified decisions together;
  • Jointly and severally, allowing them to act together or independently; or
  • In a combination for different decisions.

The donor can also appoint replacement attorneys in case an original attorney can no longer act.

These choices should be considered carefully because they affect how practical and resilient the LPA will be.

Can There Be More Than One Deputy?

The Court of Protection can appoint more than one deputy.

Where this happens, the Court order will specify how they are authorised to act.

The Court determines the arrangement rather than the person who lacks capacity setting it out personally.

Again, this highlights the difference between advance planning and court intervention after capacity has been lost.

Can Attorneys Make Health Decisions?

Only if there is an appropriate health and welfare LPA and the legal conditions for its use are satisfied.

A property and financial affairs LPA does not automatically give an attorney authority over healthcare.

Likewise, having authority over health and welfare does not automatically provide authority to manage financial affairs.

This is why many people consider making both types of LPA.

They address different areas of life.

Are Welfare Deputies Common?

The Court of Protection does not routinely appoint personal welfare deputies in the same way that property and financial affairs deputies may be appointed.

Government guidance explains that the Court will usually appoint a personal welfare deputy only in rare circumstances.

Often, welfare decisions can be made using the Mental Capacity Act’s best-interests framework without appointing a general welfare deputy.

Where there is disagreement about a significant welfare issue, the Court may instead be asked to decide the specific matter.

This is an important distinction from a health and welfare LPA, through which the donor can choose attorneys in advance.

What Is the Best-Interests Principle?

Both attorneys acting for somebody who lacks capacity and deputies appointed by the Court must operate within the Mental Capacity Act framework.

A central principle is that decisions made for a person who lacks capacity must be made in their best interests.

This does not simply mean choosing what the decision-maker personally thinks is best.

Relevant factors can include the person’s past and present wishes and feelings, beliefs and values, and the views of appropriate people involved in their welfare.

The person should also be involved in the decision as much as reasonably possible.

Can an LPA Be Cancelled?

A donor who still has mental capacity can generally revoke their LPA.

The correct formal process should be followed.

Other events can also affect an attorney’s ability to act.

For example, an attorney may choose to disclaim their appointment, and certain circumstances can terminate an appointment.

Where several attorneys are appointed, the effect on the overall LPA can depend on how they were appointed and whether replacement attorneys exist.

Legal advice can be useful before making changes.

Can a Deputy Be Removed?

Yes.

Because a deputy is appointed by the Court of Protection, changes to the appointment may require Court involvement.

The Court can remove a deputy where appropriate.

Concerns about a deputy’s conduct can also be investigated by the Office of the Public Guardian.

The system is designed to protect the person who lacks capacity rather than give the deputy permanent personal control.

What Happens When the Person Dies?

An LPA ends when the donor dies.

The attorney’s authority under the LPA does not continue for the purpose of administering the deceased person’s estate.

Likewise, deputyship authority ends when the person subject to the deputyship dies.

After death, responsibility for the estate passes to the appropriate personal representatives, such as executors under a will or administrators where there is no valid will.

This is why an LPA or deputyship should not be confused with a will.

They deal with decisions during lifetime, whereas a will primarily deals with the estate after death.

LPA vs Deputyship: Key Differences at a Glance

The simplest way to understand the distinction is to consider who makes the decision and when.

Lasting Power of Attorney

The individual makes the arrangement while they have capacity. They choose their attorney or attorneys and can express instructions and preferences.

Deputyship

The person already lacks capacity for the relevant decisions. Someone applies to the Court of Protection, and the Court decides whether to appoint a deputy and what powers that deputy should have.

Both involve significant legal responsibilities, but the route to obtaining authority is fundamentally different.

Why Planning Ahead Can Matter

Nobody can guarantee that they will always be able to manage every aspect of their affairs personally.

Illness, accidents or cognitive decline can occur unexpectedly.

An LPA provides an opportunity to decide in advance who should have authority if assistance is later required.

Without one, family members may have to seek Court of Protection authority after capacity has been lost.

Deputyship provides an essential safeguard where advance arrangements do not exist, but it involves a court process and ongoing supervision.

For many people, considering an LPA alongside their will can therefore be a sensible part of broader future planning.

Conclusion

Lasting Powers of Attorney and deputyship can both provide legal authority for somebody to make decisions on behalf of another person, but they arise in fundamentally different circumstances.

An LPA is about planning ahead.

While they still have the necessary mental capacity, the donor can choose who they trust, decide which type of authority to give them and put appropriate arrangements in place for the future.

Deputyship is generally about responding after capacity has been lost.

Where no appropriate LPA exists and decisions need to be made, an application may have to be made to the Court of Protection. The Court then determines whether a deputy should be appointed and what authority they should receive.

Deputies are also subject to Court-defined powers and ongoing supervision by the Office of the Public Guardian.

Neither arrangement gives another person unlimited control.

Attorneys and deputies have legal duties, must respect the limits of their authority and must follow the principles of the Mental Capacity Act when making decisions for somebody who lacks capacity.

The practical difference is therefore significant.

Making an LPA while capacity remains gives an individual the opportunity to make their own choice about who should act for them. Waiting until capacity has been lost may mean that the decision instead has to be made through the Court of Protection.

For anyone reviewing their will or wider estate planning, considering Lasting Powers of Attorney at the same time can help ensure that plans address not only what happens after death, but also who can assist if important decisions need to be made during their lifetime.

Power of Attorney vs Deputyship: Key Differences Read More »